Yes, usually. In Richmond, a condo or townhouse can qualify if you are 55 or older, the unit is your home, and the strata passes the lender's review. You get cash with no regular payments while interest builds and equity goes down. Building age, insurance deductibles and the strata's finances shape the answer.
Get my Equity ReportRichmond is a strata city
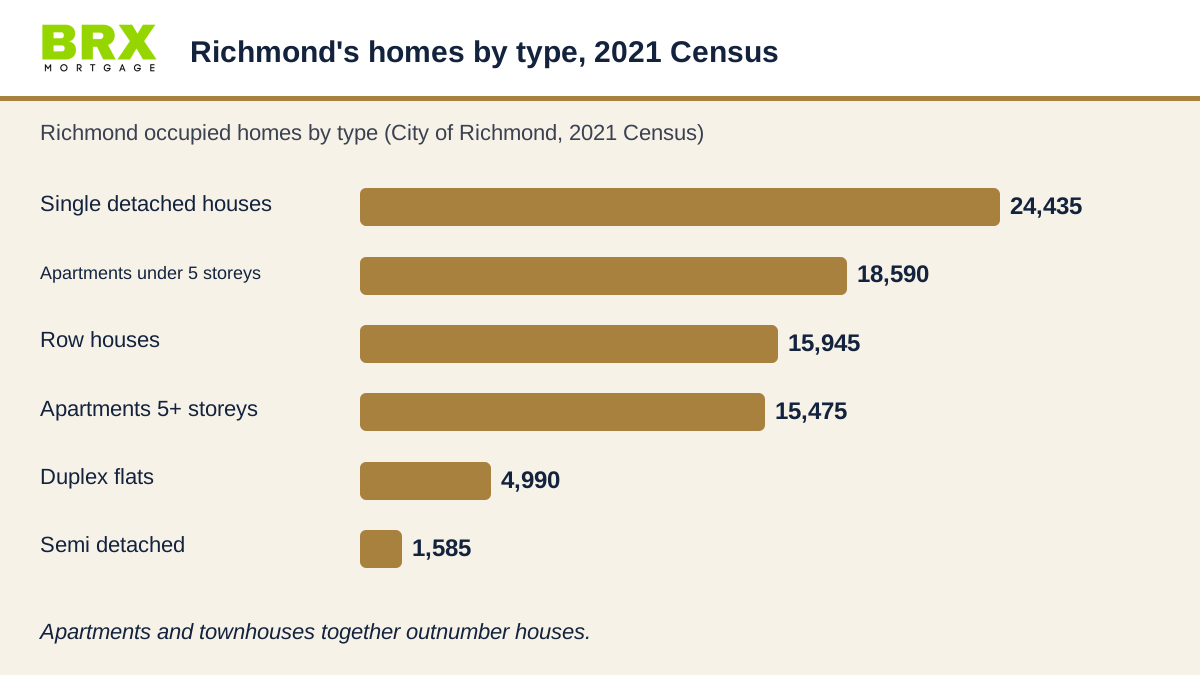
In the 2021 Census, Richmond had 81,080 occupied homes. Apartments made up 34,065 of them, split between 18,590 in buildings under five storeys and 15,475 in towers of five or more storeys. Another 15,945 were row houses or townhouses. Single detached houses numbered 24,435. Tower units grew fast, up from 10,400 in 2016, much of it in City Centre near the Canada Line.
The City also reports that the number of Richmond residents aged 65 and over nearly doubled between 2006 and 2021. So a large and growing group of older owners hold their equity in a strata home rather than a house.
For amounts on a typical Richmond strata home, see the Richmond city page. This page covers whether the unit and building will pass, which is where strata applications usually slow down.
What the lender reviews in your strata
A reverse mortgage on a strata unit is really two approvals: you and the building. Expect the lender, through the appraiser and your lawyer, to look at:
- The depreciation report and contingency reserve. A thin reserve with major work coming suggests special levies ahead.
- Recent minutes. These show planned repairs, disputes, insurance claims and levies under discussion.
- The Form B information certificate. It lists fees, levies, arrears and legal actions.
- The insurance certificate and deductibles. More on this below.
- Unit size and type. Some lenders set a minimum floor area or decline certain unit types, such as live and work units.
Ask your strata manager for these early. A building with a current depreciation report and a healthy reserve is a simpler case.
Building age: the 1980s and 1990s
Many Richmond strata buildings date from the 1980s and 1990s. The City's figures show 13,185 homes built from 1981 to 1990 and 15,510 from 1991 to 2000. In June 1998 a provincial inquiry, the Barrett Commission, reported on widespread water leaks in BC condos built in that era and made 82 recommendations. Many affected buildings were later repaired, often with a rainscreen wall system.
If your building was built in that window, the lender will want to know whether envelope work has been done, is planned, or is not needed. A completed and paid for repair is usually a plus. A large repair that is planned but not funded can delay or reduce an approval.
Earthquake deductibles on the Fraser delta
Richmond sits on the Fraser River delta, and Richmond Fire-Rescue notes that loose, water soaked soils in parts of the city can liquefy in a strong earthquake. Strata corporations are not required to buy earthquake cover, though the province strongly advises it in earthquake prone areas. The province explains that earthquake deductibles are set as a share of the building's full replacement value, not of the loss, and are passed to owners by unit entitlement.
That can mean a large personal share after a quake. Your own condo policy can cover part of it through deductible assessment cover. Lenders want the building insured and may ask about your own policy, so check your limit against your share.
Rentals and 55+ buildings
Since November 2022, BC strata corporations cannot enforce bylaws that ban or limit long term rentals. Age restriction bylaws are still allowed for residents 55 and older. Some Richmond buildings have many rented units, and lenders may look at how many owners live in the building. Being in a 55+ building does not stop you from qualifying.
Questions people ask
Will a lender accept my Richmond condo if the building had leaky condo repairs?
Often, yes. A completed and paid for envelope repair usually helps. A large repair that is planned but not yet funded can delay or reduce approval, so share the engineer's report and the minutes early.
Does Richmond's earthquake risk affect a reverse mortgage on my unit?
The lender needs the building insured, and many stratas carry earthquake cover. Check your share of the strata's earthquake deductible and whether your own condo policy covers it.
My Richmond tower has many rented units. Is that a problem?
It can lead to more questions about the building's finances and upkeep, but it does not rule you out. The lender looks at the whole strata package, not one number.
Can I get a reverse mortgage on a Richmond townhouse with a big special levy coming?
Possibly, and some owners use the funds to pay the levy. Interest builds on that money and your equity goes down, so compare it with the property tax deferment program and a payment plan from the strata.
Want your own numbers?
Get a free BC Equity Report built for your home and your age. It is an estimate, not a lender quote, and there is no obligation.
Keep reading
Sources
- City of Richmond, Housing Characteristics Hot Facts (2021 Census)
- City of Richmond, Interim Housing Needs Report
- City of Vancouver, report to Council on the Barrett Commission (July 1998)
- Richmond Fire-Rescue, Know your risks: earthquakes and tsunami
- Government of BC, Insurance for strata corporations
- Government of BC, Changes to strata legislation
- Financial Consumer Agency of Canada, reverse mortgages